01
Managed file
Completeness, consistency and knock-outs applied before the case reaches your desk. The analyst does not rebuild the file from scratch.
Origination marketplace
We prepare a managed microcredit deliverable so the institution’s subsequent analysis is more accurate. We do not lend. We do not set the rate. We are not the creditor.
The problem
Millions of independent workers generate observable economic conduct. The bureau does not read it, and a small ticket cannot carry a hand-built dossier. The outcome is not prudence: it is exclusion by cost of analysis.
Completeness, consistency and knock-outs applied before the case reaches your desk. The analyst does not rebuild the file from scratch.
Roots, productive capacity and observed commitment become a signal you can use as overlay, pre-screen or challenger.
We work against the institution’s eligibility framework. We do not auction rate. We do not build a shelf of offers.
Thesis
Artificial intelligence structures, estimates and explains. The institution’s credit policy underwrites. After disbursement, the customer is yours.
Puelo Cloud reduces noise, information asymmetry and origination cost. It does not replace your PD model or your override. The service is designed so the institution can meet the current rules of the supervisor in each market — BCRA in Argentina, CMF in Chile.
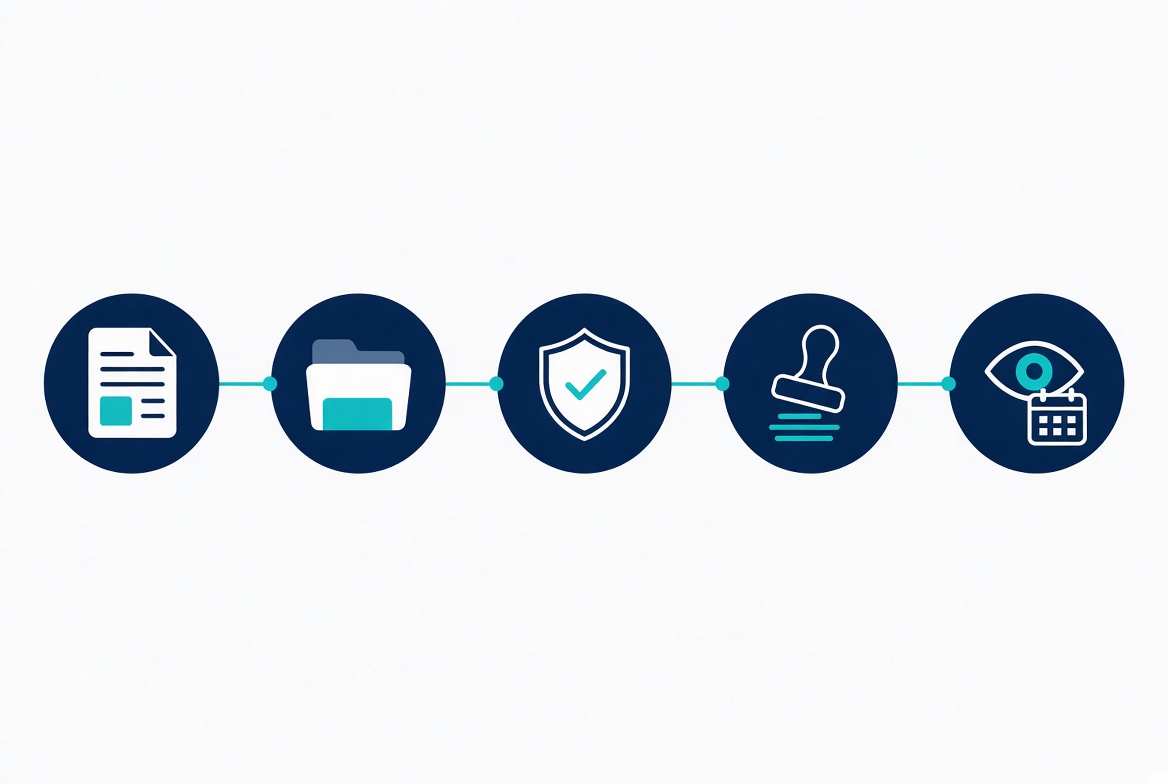
Application with consent, credit purpose and minimum eligibility data.
Synthetic signal, policy flags and required documentation. Deep identity does not travel on the rail.
The institution’s hard rules are applied. If the case is outside policy, it is not forced.
You approve, decline or request more information. You keep cut-off and veto.
Contract and primary collections sit with the lender. The origination channel observes payments for early warning and collection support.
Economics
The funder sets price, tenor and limit. We charge for sound origination and for signal quality — not for inflating the borrower’s rate.
Audience
This site speaks to Risk, Origination and Product. Distribution partners and capital have their own door.
Microcredit origination with a lower file cost, your own eligibility policy, and a pack that makes subsequent analysis more accurate.
Underwriting · PD · cut-off · NPL
info-finanzas@puelo.cloudNetworks and platforms that concentrate qualified demand and need an orderly way to originate toward an institution.
Distribution · consent · volume
info-integradores@puelo.cloudThose who fund origination infrastructure — not the lender’s loan book.
Risk infrastructure · B2B
info-investment@puelo.cloud